Inheritance Tax (IHT) remains one of the most misunderstood areas of UK tax law. Despite affecting thousands of families each year, myths and half-truths continue to circulate: particularly around the infamous “7-year rule.” With property values rising and frozen tax thresholds, more estates are being drawn into the IHT net.
If you’re worried about how much of your hard-earned wealth will actually reach your children or grandchildren, you’re not alone. The good news? With proper inheritance tax planning advice, there are legitimate strategies to protect your family’s financial future.
TL;DR
- Inheritance Tax is charged at 40% on the value of an estate above the £325,000 nil-rate band.
- The £175,000 residence nil-rate band can take the allowance to £500,000, or up to £1 million for married couples and civil partners.
- Gifts only become fully exempt if you survive seven years, with taper relief reducing the tax on gifts made three to seven years before death.
- Giving away your home but continuing to live in it rent-free means it still counts as part of your estate.
- Writing a life insurance policy in trust keeps the payout outside your estate.
Understanding UK Inheritance Tax in 2026
Inheritance Tax is charged at 40% on the value of your estate above the tax-free threshold when you die. For most people, that threshold: called the nil-rate band: sits at £325,000. If you own a home that you’re passing to direct descendants, you may also qualify for the residence nil-rate band of £175,000, bringing your total tax-free allowance to up to £500,000.
For married couples and civil partners, these allowances can be combined, potentially protecting up to £1 million from IHT. But here’s the catch: those thresholds have been frozen since 2009 (for the nil-rate band) and 2020 (for the residence band), while house prices in London, Windsor, and across the South East have soared.
The result? A growing number of “accidental millionaires”: ordinary homeowners who never considered themselves wealthy: are now facing substantial IHT bills for their families.
Myth 1: “I Can Just Give Everything Away Now”
Perhaps the most dangerous misconception is that you can simply gift away your assets and immediately escape IHT. Many people believe that once they’ve transferred money or property to their children, it’s no longer part of their estate. Unfortunately, HMRC doesn’t make it that simple.
Gifts made during your lifetime can still be subject to IHT if you die within seven years of making them. These are known as “potentially exempt transfers” (PETs). The key word here is potentially: they only become fully exempt if you survive seven years after making the gift.
Even more problematic are “gifts with reservation of benefit.” If you give your house to your children but continue living in it rent-free, HMRC will treat that property as still being part of your estate. You can’t have your cake and eat it too.
Myth 2: “The 7-Year Rule Means I’m Safe After Seven Years”
The 7-year rule is real, but it’s often misunderstood. Here’s how it actually works:
If you make a large gift (above your annual exemptions) and survive for seven full years, that gift usually falls outside your estate for IHT purposes. However, if you die within those seven years, the gift may be taxed: though there’s a sliding scale of relief called taper relief.
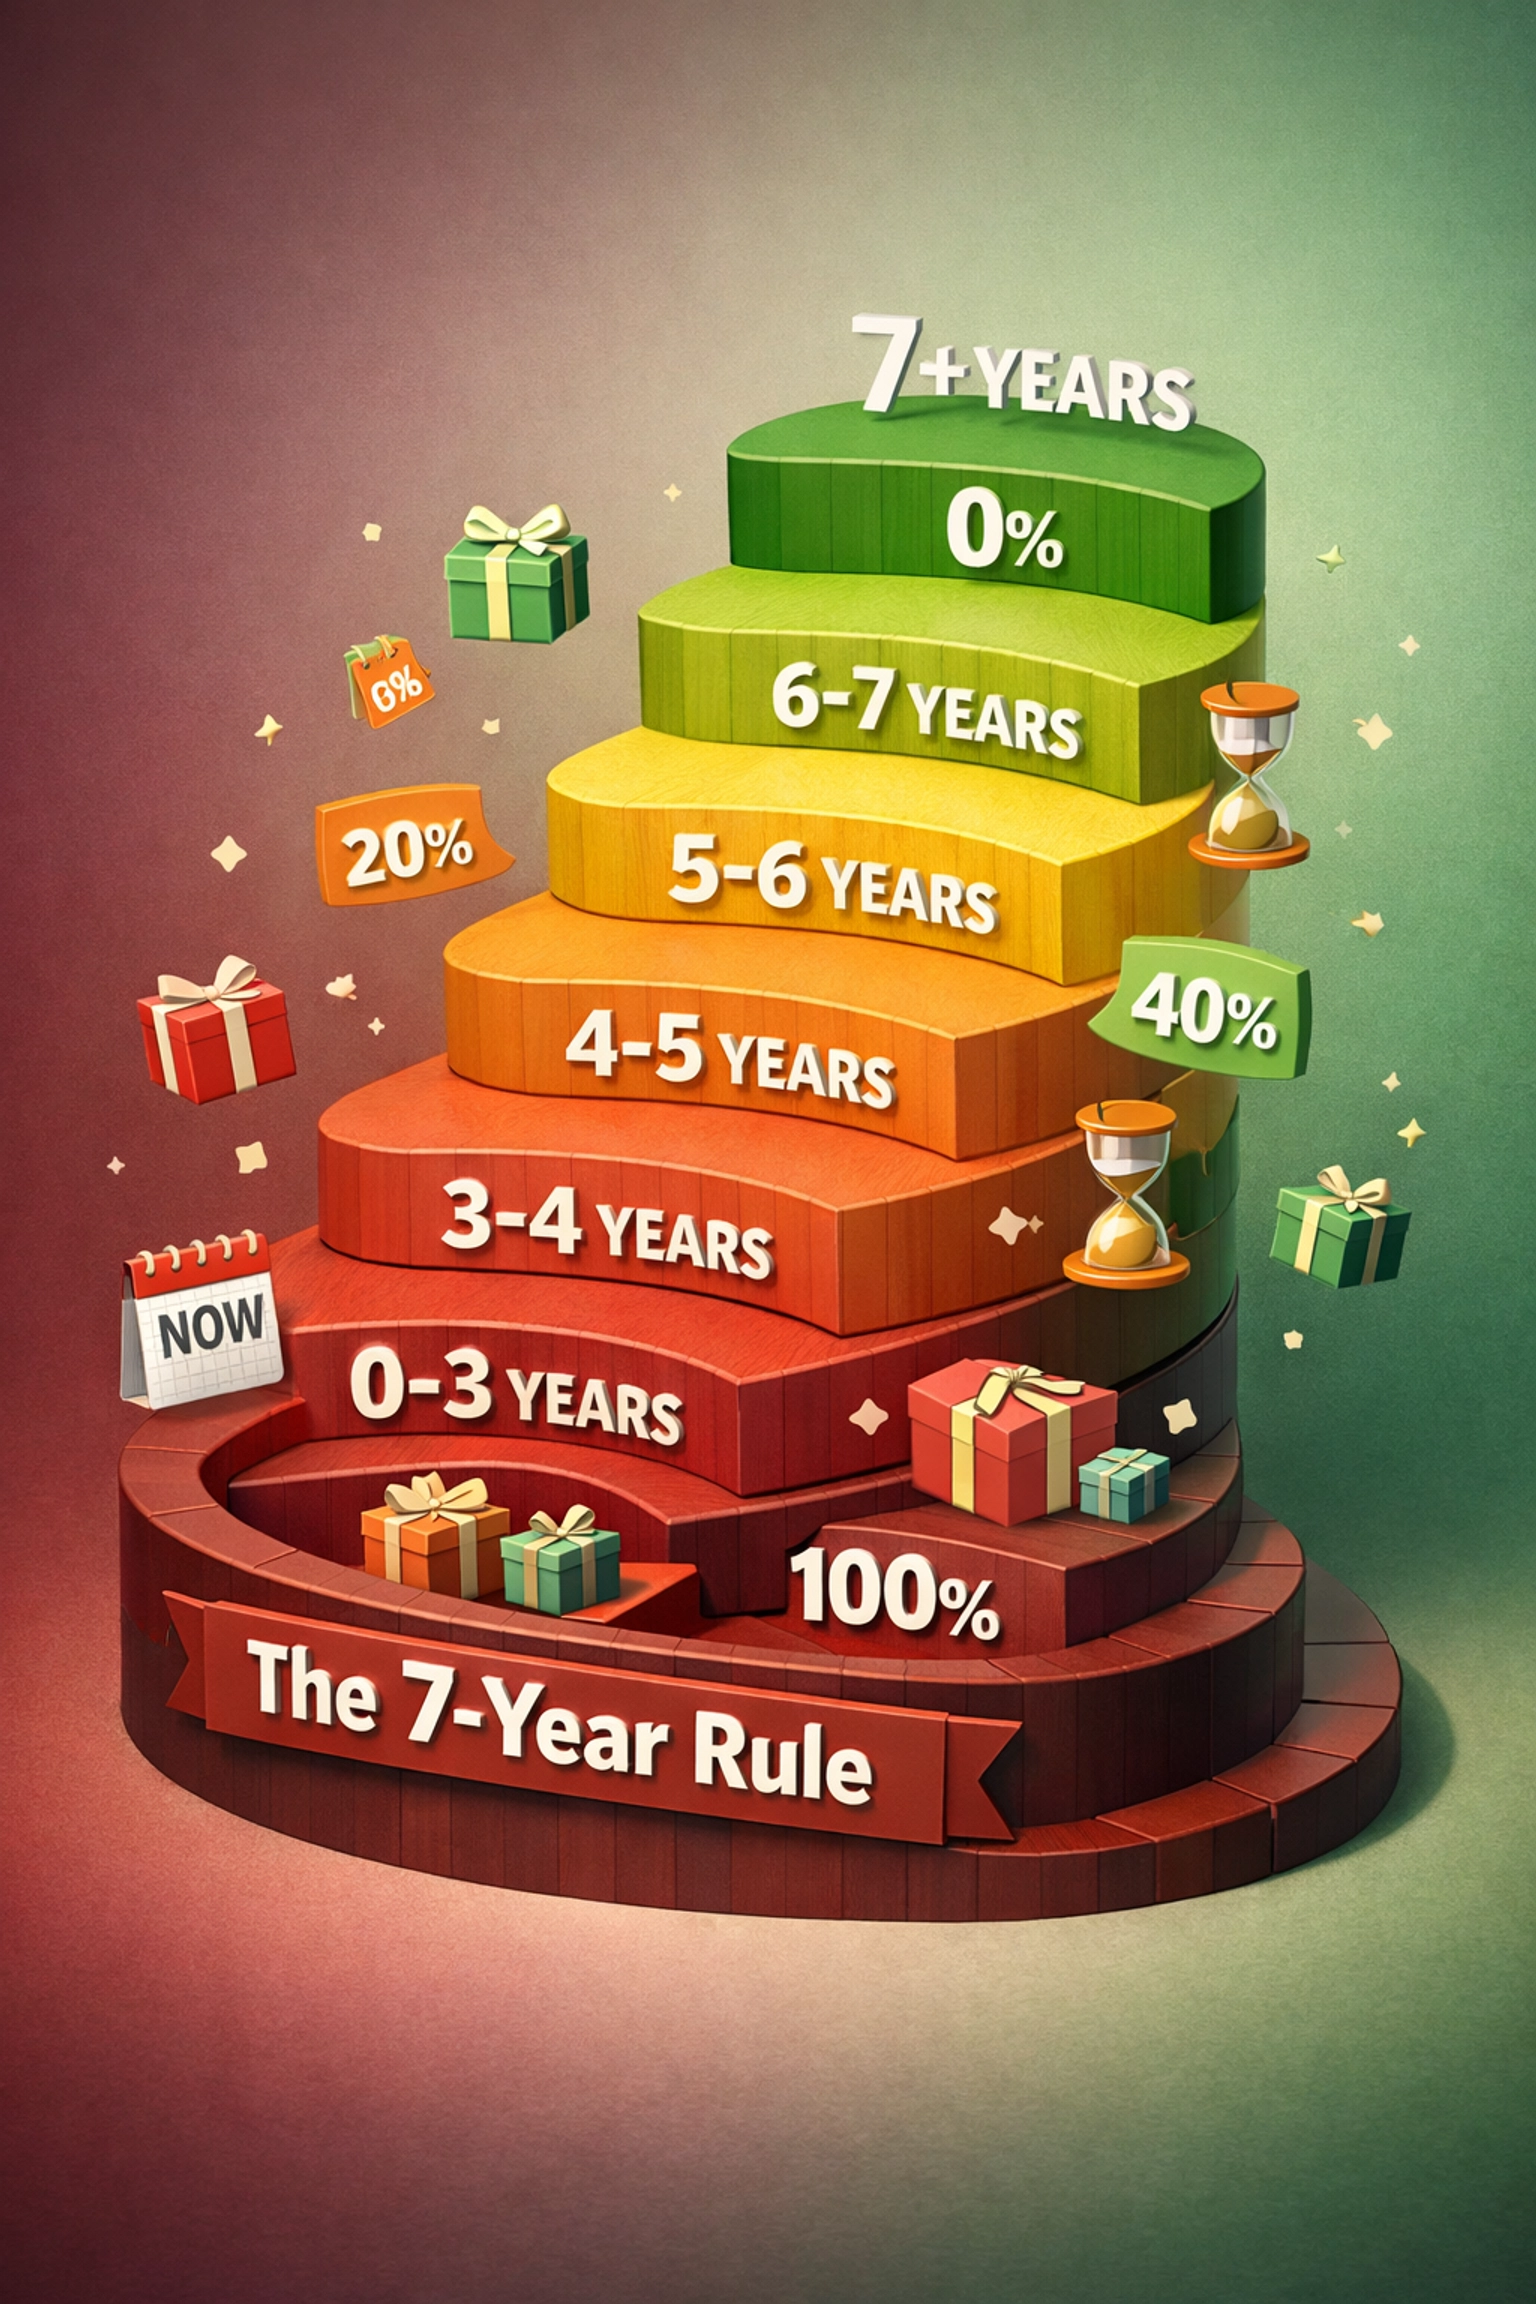
The Taper Relief Scale:
- Years 0-3: No relief: full 40% IHT applies
- Years 3-4: 20% relief (32% effective tax rate)
- Years 4-5: 40% relief (24% effective tax rate)
- Years 5-6: 60% relief (16% effective tax rate)
- Years 6-7: 80% relief (8% effective tax rate)
- 7+ years: Gift is fully exempt
But here’s the crucial detail most people miss: taper relief only applies if the gift itself exceeds the nil-rate band. If the total value of gifts in the seven years before death is less than £325,000, no IHT is due on the gifts anyway. Taper relief only helps reduce tax on gifts that push the estate over the threshold.
Myth 3: “Trusts Are Only for the Super-Rich”
When you hear the word “trust,” you might picture aristocratic families managing vast country estates. In reality, trusts are practical planning tools that can benefit a wide range of families: particularly those with property wealth in London and the South East.
A properly structured trust can:
- Help plan for future care costs (although a local authority can treat assets given away to avoid care fees as still yours)
- Ring-fence inheritance for children from previous marriages
- Provide for vulnerable beneficiaries who can’t manage money
- Reduce or eliminate IHT liabilities over time
The most commonly used trust for IHT planning is a discretionary trust. While assets placed into this type of trust may incur an immediate IHT charge (usually 20% if above the nil-rate band), the assets then sit outside your estate. Growth in value after the transfer is also outside your estate, which can make them useful for younger individuals with significant assets, although the trust itself can face a charge of up to 6% at each ten-year anniversary and exit charges when assets leave it.
For married couples, nil-rate band discretionary trusts used to be standard practice before 2007. While transferable nil-rate bands have made them less essential, they’re still valuable in second marriages, and are sometimes considered where there are concerns about future care costs (subject to the deprivation of assets rules).
Myth 4: “Life Insurance Doesn’t Count Towards My Estate”
Many people take out life insurance policies specifically to cover an anticipated IHT bill. The logic seems sound: you die, the policy pays out £200,000, and your family uses it to pay HMRC. Problem solved.
Except there’s a catch. If the life insurance policy is written in your own name, the payout becomes part of your taxable estate. You’ve just increased your IHT liability rather than solving it.
The solution? Write your life insurance policy in trust. This ensures the payout goes directly to your beneficiaries outside your estate, bypassing probate and IHT altogether. It’s a simple administrative step that many people overlook: and it costs nothing to set up.
Practical Strategies That Actually Work
Beyond understanding the myths, let’s look at legitimate strategies for protecting family wealth in 2026.
Use Your Annual Exemptions
Every UK taxpayer can give away £3,000 per year without it counting towards your estate. You can also make unlimited small gifts of up to £250 per person (as long as you haven’t used another exemption for that person).
Wedding gifts have their own exemptions: £5,000 to a child, £2,500 to a grandchild, and £1,000 to anyone else.
Regular gifts from surplus income are also exempt, provided you can demonstrate they don’t affect your standard of living. This is particularly useful for grandparents who want to help with school fees.
Consider Business Property Relief and Agricultural Property Relief
If you own a trading business or farm, you may qualify for 100% relief from IHT on those assets, usually provided you’ve owned them for at least two years before death. Since 6 April 2026, 100% relief applies only to the first £2.5 million of combined qualifying business and agricultural property, with 50% relief on the excess. This relief is one of the most powerful in the UK tax system: but it’s complex and subject to strict conditions.
Even shares in certain unlisted trading companies can qualify. This has led to the growth of “IHT portfolios” invested in qualifying Alternative Investment Market (AIM) shares, though these carry investment risk and aren’t suitable for everyone. Since 6 April 2026, qualifying AIM shares receive 50% relief rather than 100%.
Make Use of Pension Death Benefits
Since 2015, pensions have been one of the most tax-efficient ways to pass on wealth. For deaths before 6 April 2027, most pensions sit outside your estate for IHT purposes. For deaths on or after 6 April 2027, the Finance Act 2026 brings most unused pension funds and pension death benefits into your estate for IHT. Death-in-service benefits are excluded, and pensions left to a spouse or civil partner remain covered by the spouse exemption.
If you die before age 75, your beneficiaries can usually receive your pension free of income tax. After 75, they’ll pay income tax at their marginal rate. For deaths on or after 6 April 2027, IHT may also be due on the pension.
This makes it important to review how your pension fits into your wider estate plan before the April 2027 change takes effect.
The Residence Nil-Rate Band Trap
While the £175,000 residence nil-rate band sounds generous, it comes with strings attached. It only applies if:
- You leave your home to direct descendants (children, grandchildren, stepchildren)
- Your estate is worth £2 million or less (above that, the band is tapered)
- You still own a residential property (or downsized after July 2015 and left equivalent value to descendants)
The band is also tapered away by £1 for every £2 your estate exceeds £2 million. For a single person with an estate of £2.35 million or more, the residence nil-rate band disappears entirely; where a surviving spouse or civil partner can also claim their late partner’s unused band, it disappears at £2.7 million.
When to Seek Professional Advice
Inheritance tax planning isn’t a DIY project: especially in 2026, when the rules are more complex than ever. A poorly drafted will or badly timed gift can cost your family tens or even hundreds of thousands of pounds.
You should particularly consider professional advice if you:
- Own property worth more than £500,000 (or £1 million as a couple)
- Have been married more than once or have stepchildren
- Own a business or shares in a family company
- Have made significant lifetime gifts in the past seven years
- Want to protect assets from future care home fees
The earlier you start planning, the more options you’ll have. IHT planning works best when you have time on your side: which means addressing it while you’re healthy and well, not as an urgent last-minute exercise.
Frequently asked questions
How much can I leave before Inheritance Tax is due?
The nil-rate band is £325,000. If you leave your home to direct descendants, the £175,000 residence nil-rate band can take this to £500,000, and married couples and civil partners can combine their allowances, potentially protecting up to £1 million.
What happens if I die within seven years of making a gift?
The gift may be taxed. Taper relief reduces the tax on gifts made three to seven years before death, but it only helps where the gifts exceed the £325,000 nil-rate band.
Can I give my house to my children and keep living in it?
If you continue living in it rent-free, HMRC treats it as a gift with reservation of benefit, so the property still counts as part of your estate.
How much can I give away each year without it counting towards my estate?
You can give away £3,000 a year, plus small gifts of up to £250 per person where no other exemption has been used for that person. Wedding gifts have their own exemptions: £5,000 to a child, £2,500 to a grandchild and £1,000 to anyone else.
Is a life insurance payout subject to Inheritance Tax?
If the policy is written in your own name, the payout becomes part of your taxable estate. Writing the policy in trust means the payout goes to your beneficiaries outside your estate.
Who qualifies for the residence nil-rate band?
It applies if you leave your home to direct descendants, such as children, grandchildren or stepchildren. Where the estate is worth more than £2 million, it is reduced by £1 for every £2 over that amount.
Final Thoughts
Inheritance Tax doesn’t have to devastate your family’s finances. Despite the myths and misconceptions, there are legitimate strategies to reduce or eliminate IHT: but they require understanding, planning, and professional guidance.
The 7-year rule isn’t a magic wand that makes your assets disappear. Trusts aren’t just for the aristocracy. And giving away your home while continuing to live in it won’t fool HMRC.
What will work is a comprehensive, properly structured estate plan that uses all the available reliefs and exemptions while protecting your own financial security. That’s where wills and estate planning advice makes all the difference.
After all, you’ve spent a lifetime building wealth for your family. With the right planning, you can make sure they actually receive it.